;%20}%20.cls-2%20{%20fill:%20%2332527e;%20}%20.cls-3%20{%20fill:%20url(%23linear-gradient);%20}%20.cls-4%20{%20fill:%20%23fff;%20}%20.cls-5%20{%20fill:%20%237eb458;%20}%20%3c/style%3e%3clinearGradient%20id='linear-gradient'%20x1='10.79'%20y1='90.08'%20x2='20.45'%20y2='39.65'%20gradientTransform='translate(0%20102.96)%20scale(1%20-1)'%20gradientUnits='userSpaceOnUse'%3e%3cstop%20offset='0'%20stop-color='%23bed891'/%3e%3cstop%20offset='1'%20stop-color='%233a8940'/%3e%3c/linearGradient%3e%3clinearGradient%20id='linear-gradient-2'%20x1='10.13'%20y1='69.7'%20x2='19.43'%20y2='46.06'%20gradientTransform='translate(0%20102.96)%20scale(1%20-1)'%20gradientUnits='userSpaceOnUse'%3e%3cstop%20offset='0'%20stop-color='%23e8eed6'/%3e%3cstop%20offset='.93'%20stop-color='%237eb25a'/%3e%3c/linearGradient%3e%3c/defs%3e%3cg%3e%3cpath%20class='cls-3'%20d='M37.97,51.84c-1.95-6.94-5.83-11.07-12.29-17.47h0c-8.39-9.15-11.09-22.94-11.09-22.94-1.59,2.09-2,8.17-2.11,9.84C7.68,16.09,4.01,9.92,6.48,0,6.48,0-.17,12.82,3.57,21.22c2.02,4.53,2.59,8.54,2.38,12.22-1.71-1.33-3.11-3.3-4.08-7.43-2.49,9.75,2.38,11.89,1.79,17.64-2.18,6.31-4.84,12.13-3.09,18.97,2.44,9.52,12,16.63,23.56,13.51,11.54-3.14,16.36-15.35,13.84-24.29Z'/%3e%3cpath%20class='cls-1'%20d='M35.93,57.33c-3.07-16.06-19.81-17-25.14-29.03,2.79,10.01-.18,16.27-3.67,22.38-1.69,2.97-3.01,8.68-1.55,13.49,1.69,5.58,10.28,15.27,21.05,11.09,3.78-1.75,5.87-3.4,8.5-7.02,1.61-3.31,1.48-7.41.81-10.91Z'/%3e%3cpath%20class='cls-4'%20d='M34.63,61.41c1.58,5.85-1.89,11.86-7.73,13.44-5.85,1.58-11.86-1.89-13.44-7.73-2.43-9.03,4.94-13.06,5.75-20.8-.42,7.73,13.04,6.24,15.42,15.09Z'/%3e%3c/g%3e%3cg%3e%3cpath%20class='cls-2'%20d='M54.57,39.71v14.72h21.18v5.19h-21.18v17.08h-6.03v-42.24h29.8v5.25h-23.77Z'/%3e%3cpath%20class='cls-2'%20d='M112.46,44.72v31.98h-5.49v-4.83c-2.35,3.32-6.34,5.19-10.86,5.19-8.27,0-13.76-4.53-13.76-13.94v-18.4h5.79v17.74c0,6.28,3.14,9.41,8.63,9.41,6.03,0,9.89-3.74,9.89-10.62v-16.53h5.8Z'/%3e%3cpath%20class='cls-2'%20d='M117.26,73.32l2.41-4.59c2.71,1.93,7.06,3.32,11.22,3.32,5.37,0,7.6-1.63,7.6-4.34,0-7.18-20.21-.97-20.21-13.7,0-5.73,5.13-9.6,13.33-9.6,4.16,0,8.87,1.09,11.64,2.9l-2.47,4.59c-2.9-1.87-6.09-2.53-9.23-2.53-5.07,0-7.54,1.87-7.54,4.4,0,7.54,20.27,1.39,20.27,13.82,0,5.79-5.31,9.47-13.82,9.47-5.3,0-10.55-1.63-13.2-3.74Z'/%3e%3cpath%20class='cls-2'%20d='M180.29,62.64h-25.94c.72,5.61,5.25,9.35,11.58,9.35,3.74,0,6.88-1.27,9.23-3.86l3.2,3.74c-2.9,3.38-7.3,5.19-12.61,5.19-10.32,0-17.19-6.82-17.19-16.35s6.82-16.29,16.05-16.29,15.81,6.64,15.81,16.47c0,.48-.07,1.2-.13,1.75ZM154.35,58.47h20.51c-.6-5.37-4.65-9.17-10.26-9.17-5.54,0-9.65,3.74-10.25,9.17Z'/%3e%3cpath%20class='cls-5'%20d='M215.82,58.29v18.4h-5.79v-17.74c0-6.28-3.14-9.35-8.63-9.35-6.15,0-10.13,3.68-10.14,10.62v16.47h-5.79v-31.98h5.55v4.83c2.35-3.26,6.45-5.13,11.52-5.13,7.79,0,13.28,4.47,13.28,13.88Z'/%3e%3c/g%3e%3c/svg%3e)
Description
Project Profile: X.7 Swing Intraday
1. Strategic Identity and Quantitative Solution
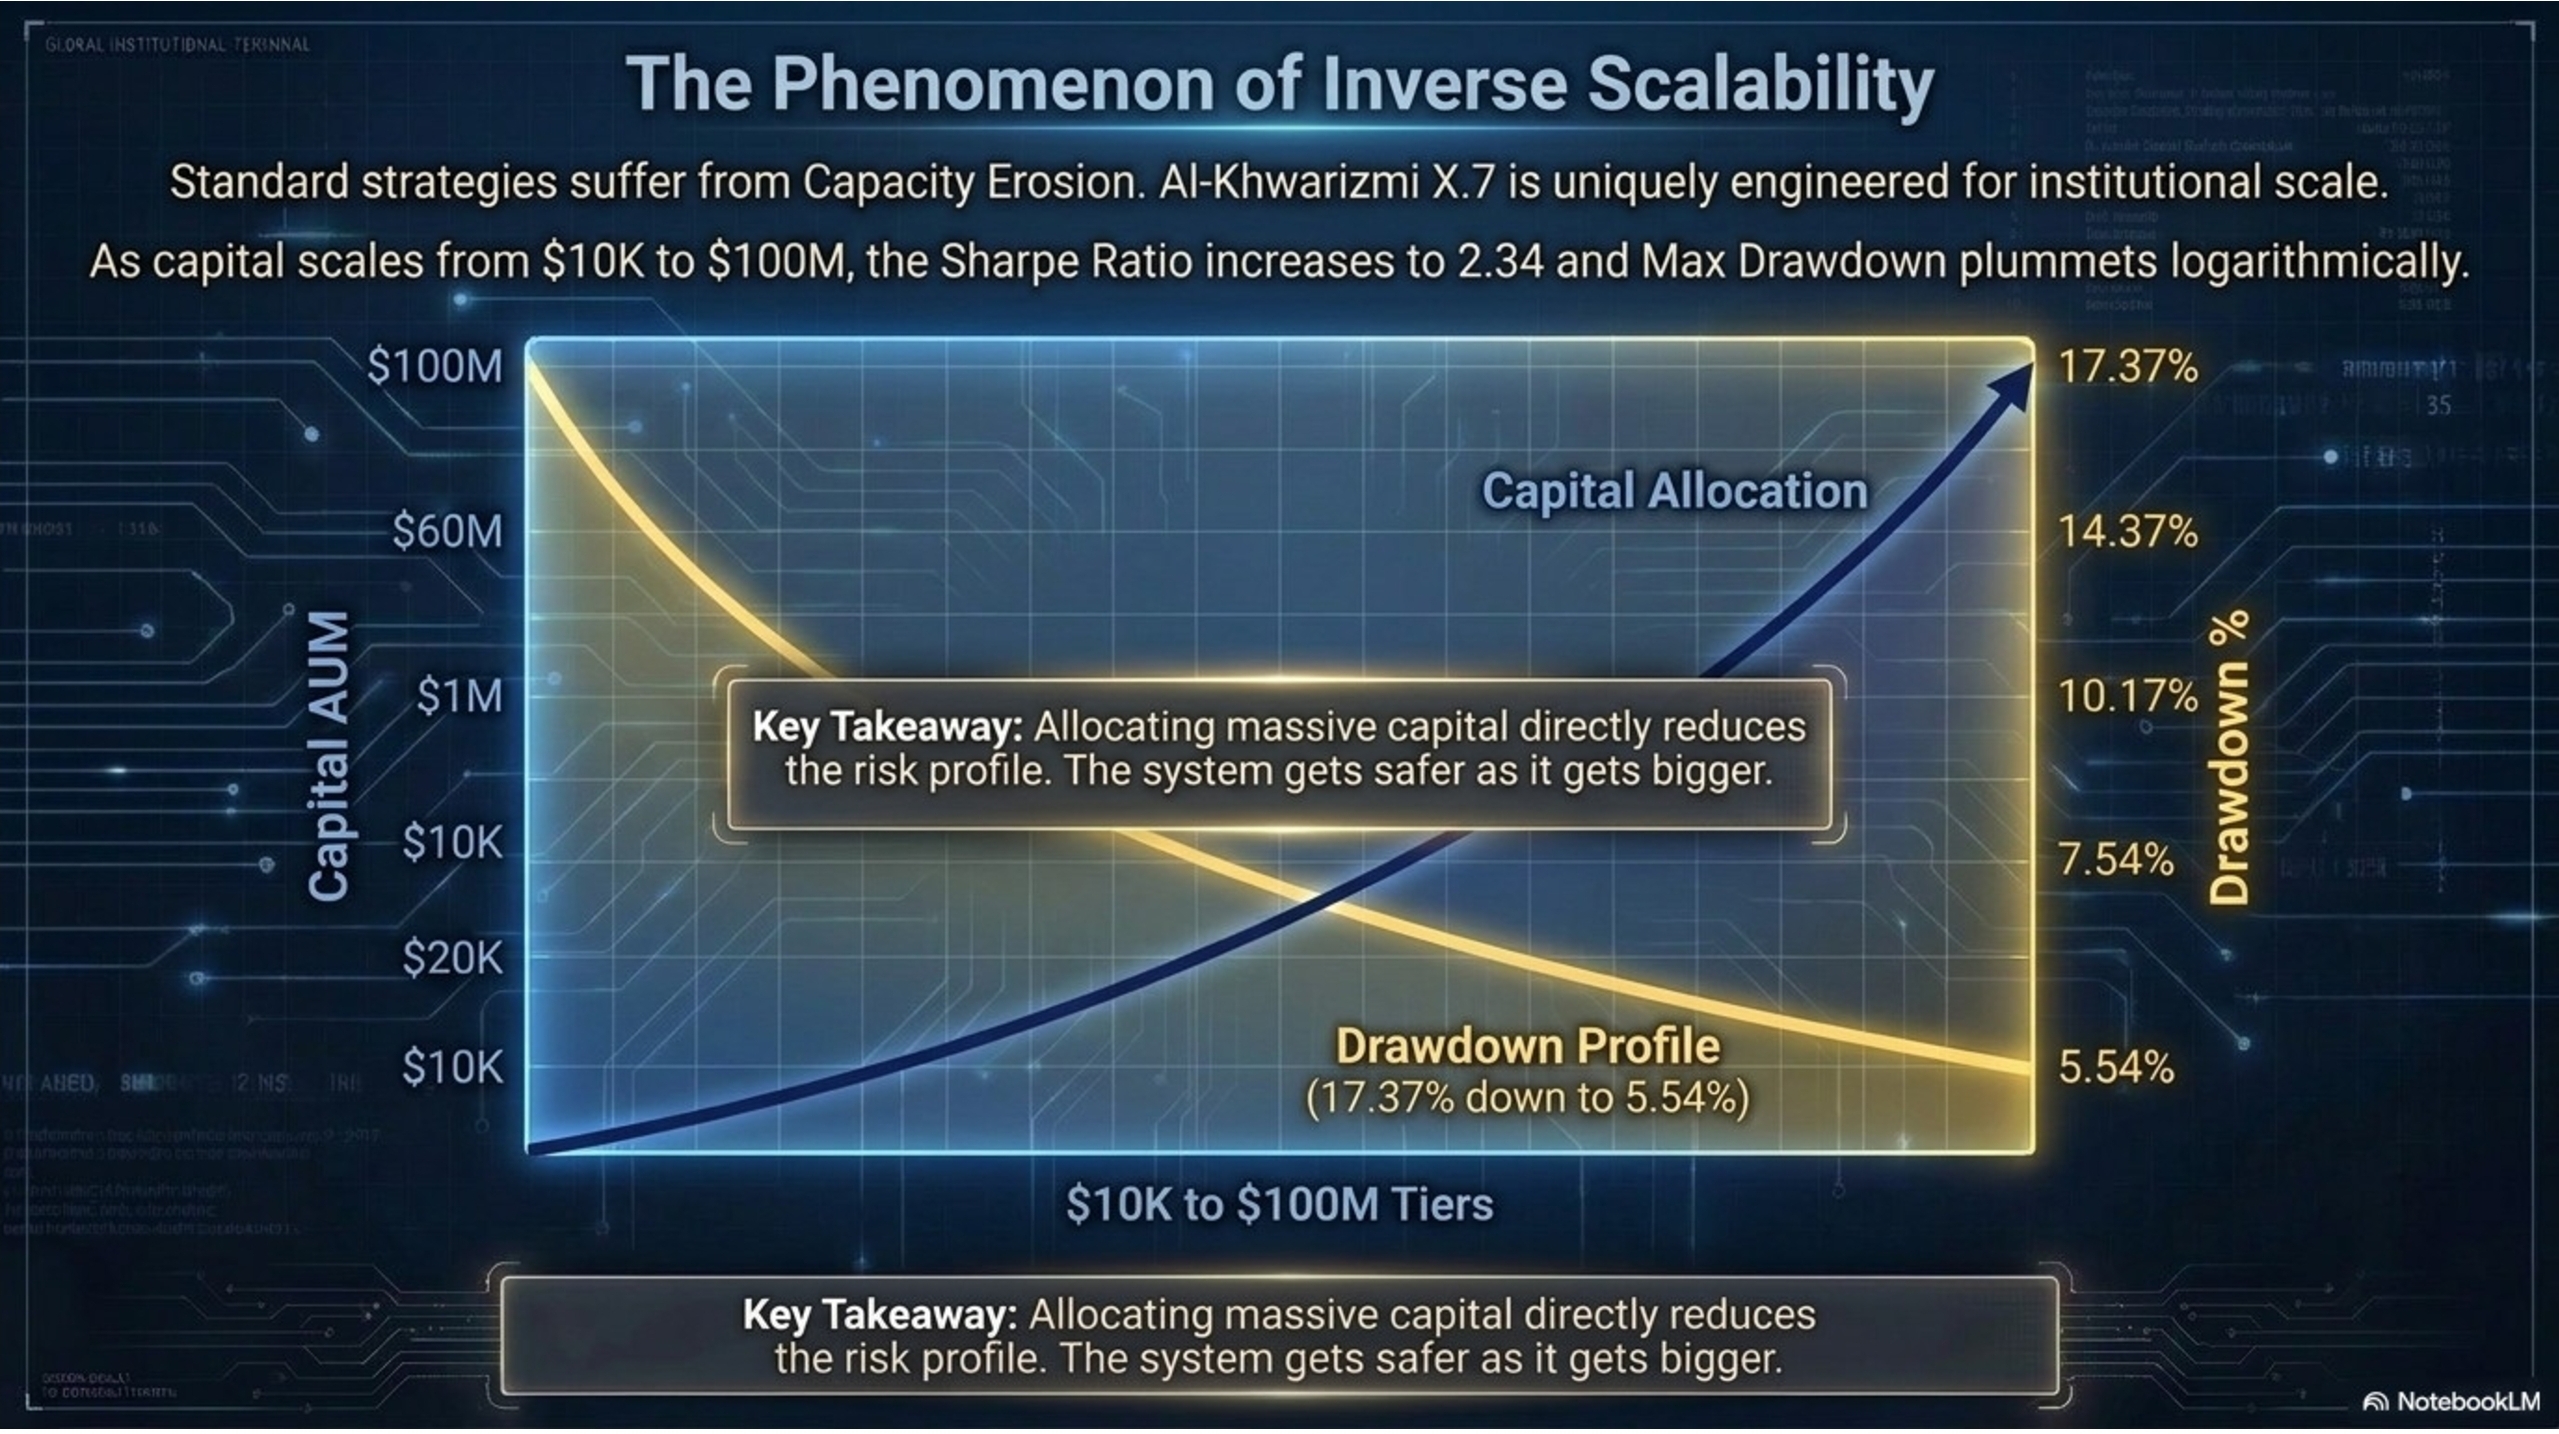
The X.7 Swing Intraday is a proprietary quantitative investment engine designed for Systematic Mean Reversion within the XAUUSD (Spot Gold) market. The architecture is specifically engineered to mitigate the systemic failures prevalent in retail algorithmic trading: overfitting (historical curve-fitting) and capacity erosion (performance degradation at scale). By utilizing a 99% tick data modeling foundation, the system effectively neutralizes real-world execution friction, slippage, and latency, ensuring institutional-grade fidelity. The engine operates on a structural principle of Inverse Scalability; unlike traditional strategies where risk increases with volume, the X.7 risk profile improves as capital scales toward the $100M threshold, with drawdowns decreasing logarithmically as AUM grows. This pivot transforms liquidity depth into a structural alpha advantage, exploiting recurring macroeconomic imbalances.
2. Market Dynamics and Alpha Opportunity
The engine’s edge is derived from the XAUUSD micro-structure, which is governed by the friction between safe-haven demand, real yield fluctuations, and central bank allocations. These competing forces create cyclical overbought and oversold extremes that the engine captures via a multi-dimensional filter comprising TEMA trend detection, RSI extreme detection, and RVI momentum depletion. The system’s mathematical robustness has been validated across distinct macroeconomic regimes:
* Extreme Volatility: Successfully navigated the 2020 global pandemic liquidity shocks.
* Pessimistic Trending: Maintained structural stability during the 2022 geopolitical instability and market saturation.
* Optimal Oscillatory Markets: Captured significant alpha during the Advanced Out-of-Sample Validation period (2024–2026) amid historic gold price appreciation.
This performance is not a temporal anomaly but the empirical result of 8,844 analyzed trades, proving a sustained statistical edge in high-liquidity environments.
3. Institutional Performance Metrics (Validated Results)
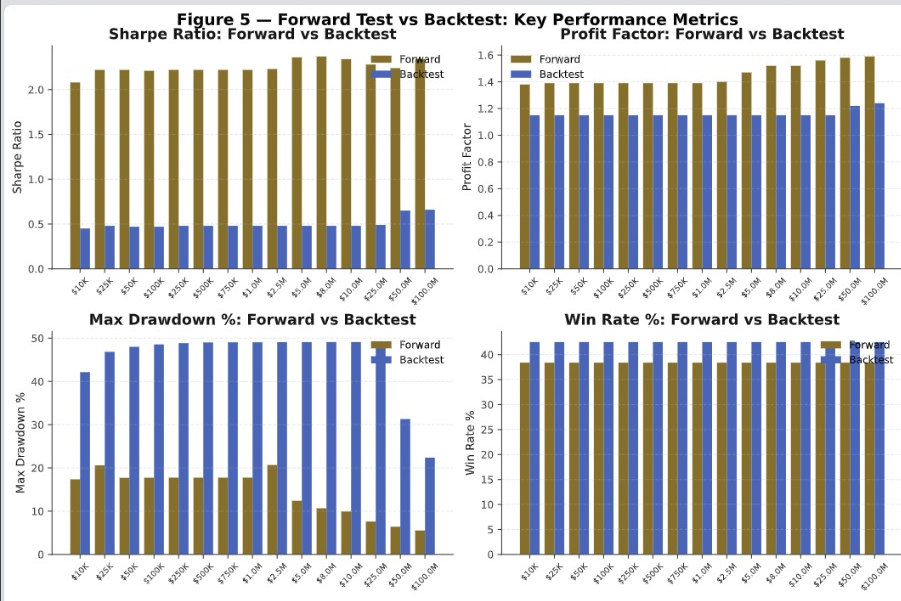
The following metrics summarize the 7.31-year validation horizon, which includes 5 years of in-sample training and 2.4 years of advanced out-of-sample forward verification. A 1,000-path Monte Carlo simulation confirms a Zero Ruin profile, demonstrating that the engine's profitability is mathematically immune to specific trade sequences.
Metric Validated Outcome ($50M Base Case)
Initial Capitalization $50,000,000
Final Validated Equity $393,975,786
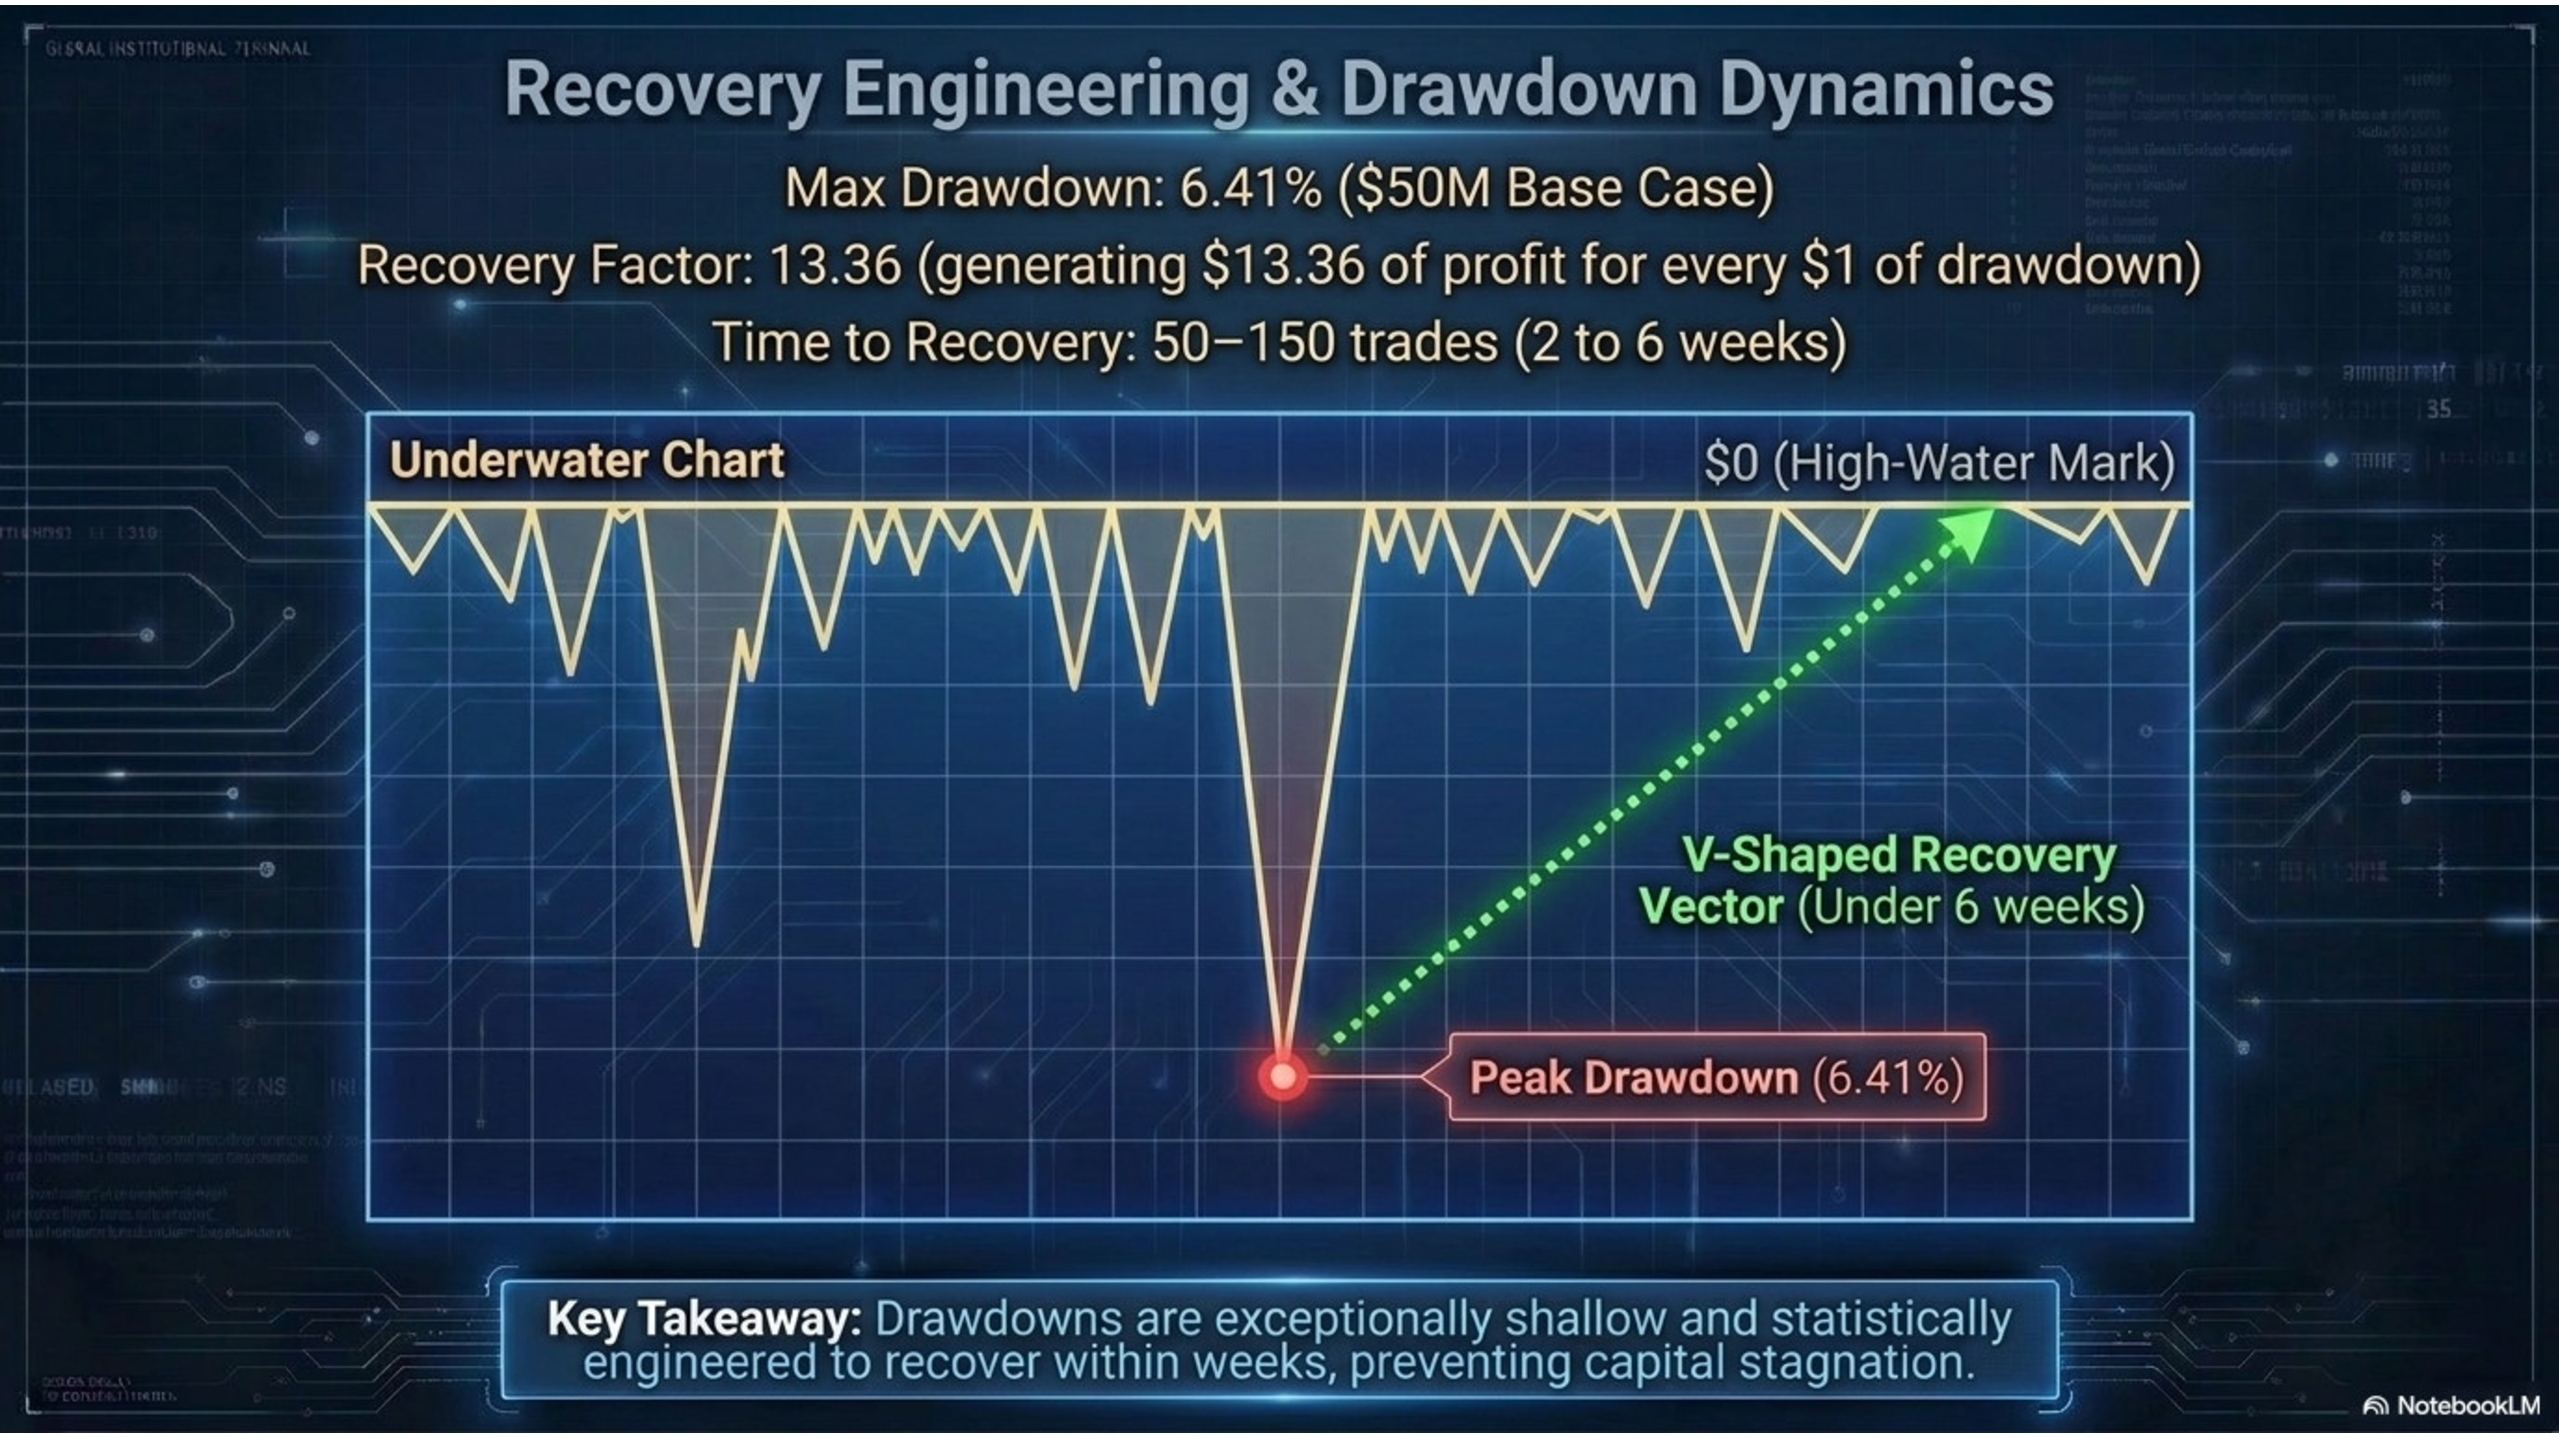
Maximum Drawdown (MDD) 6.41%
Recovery Factor 13.36
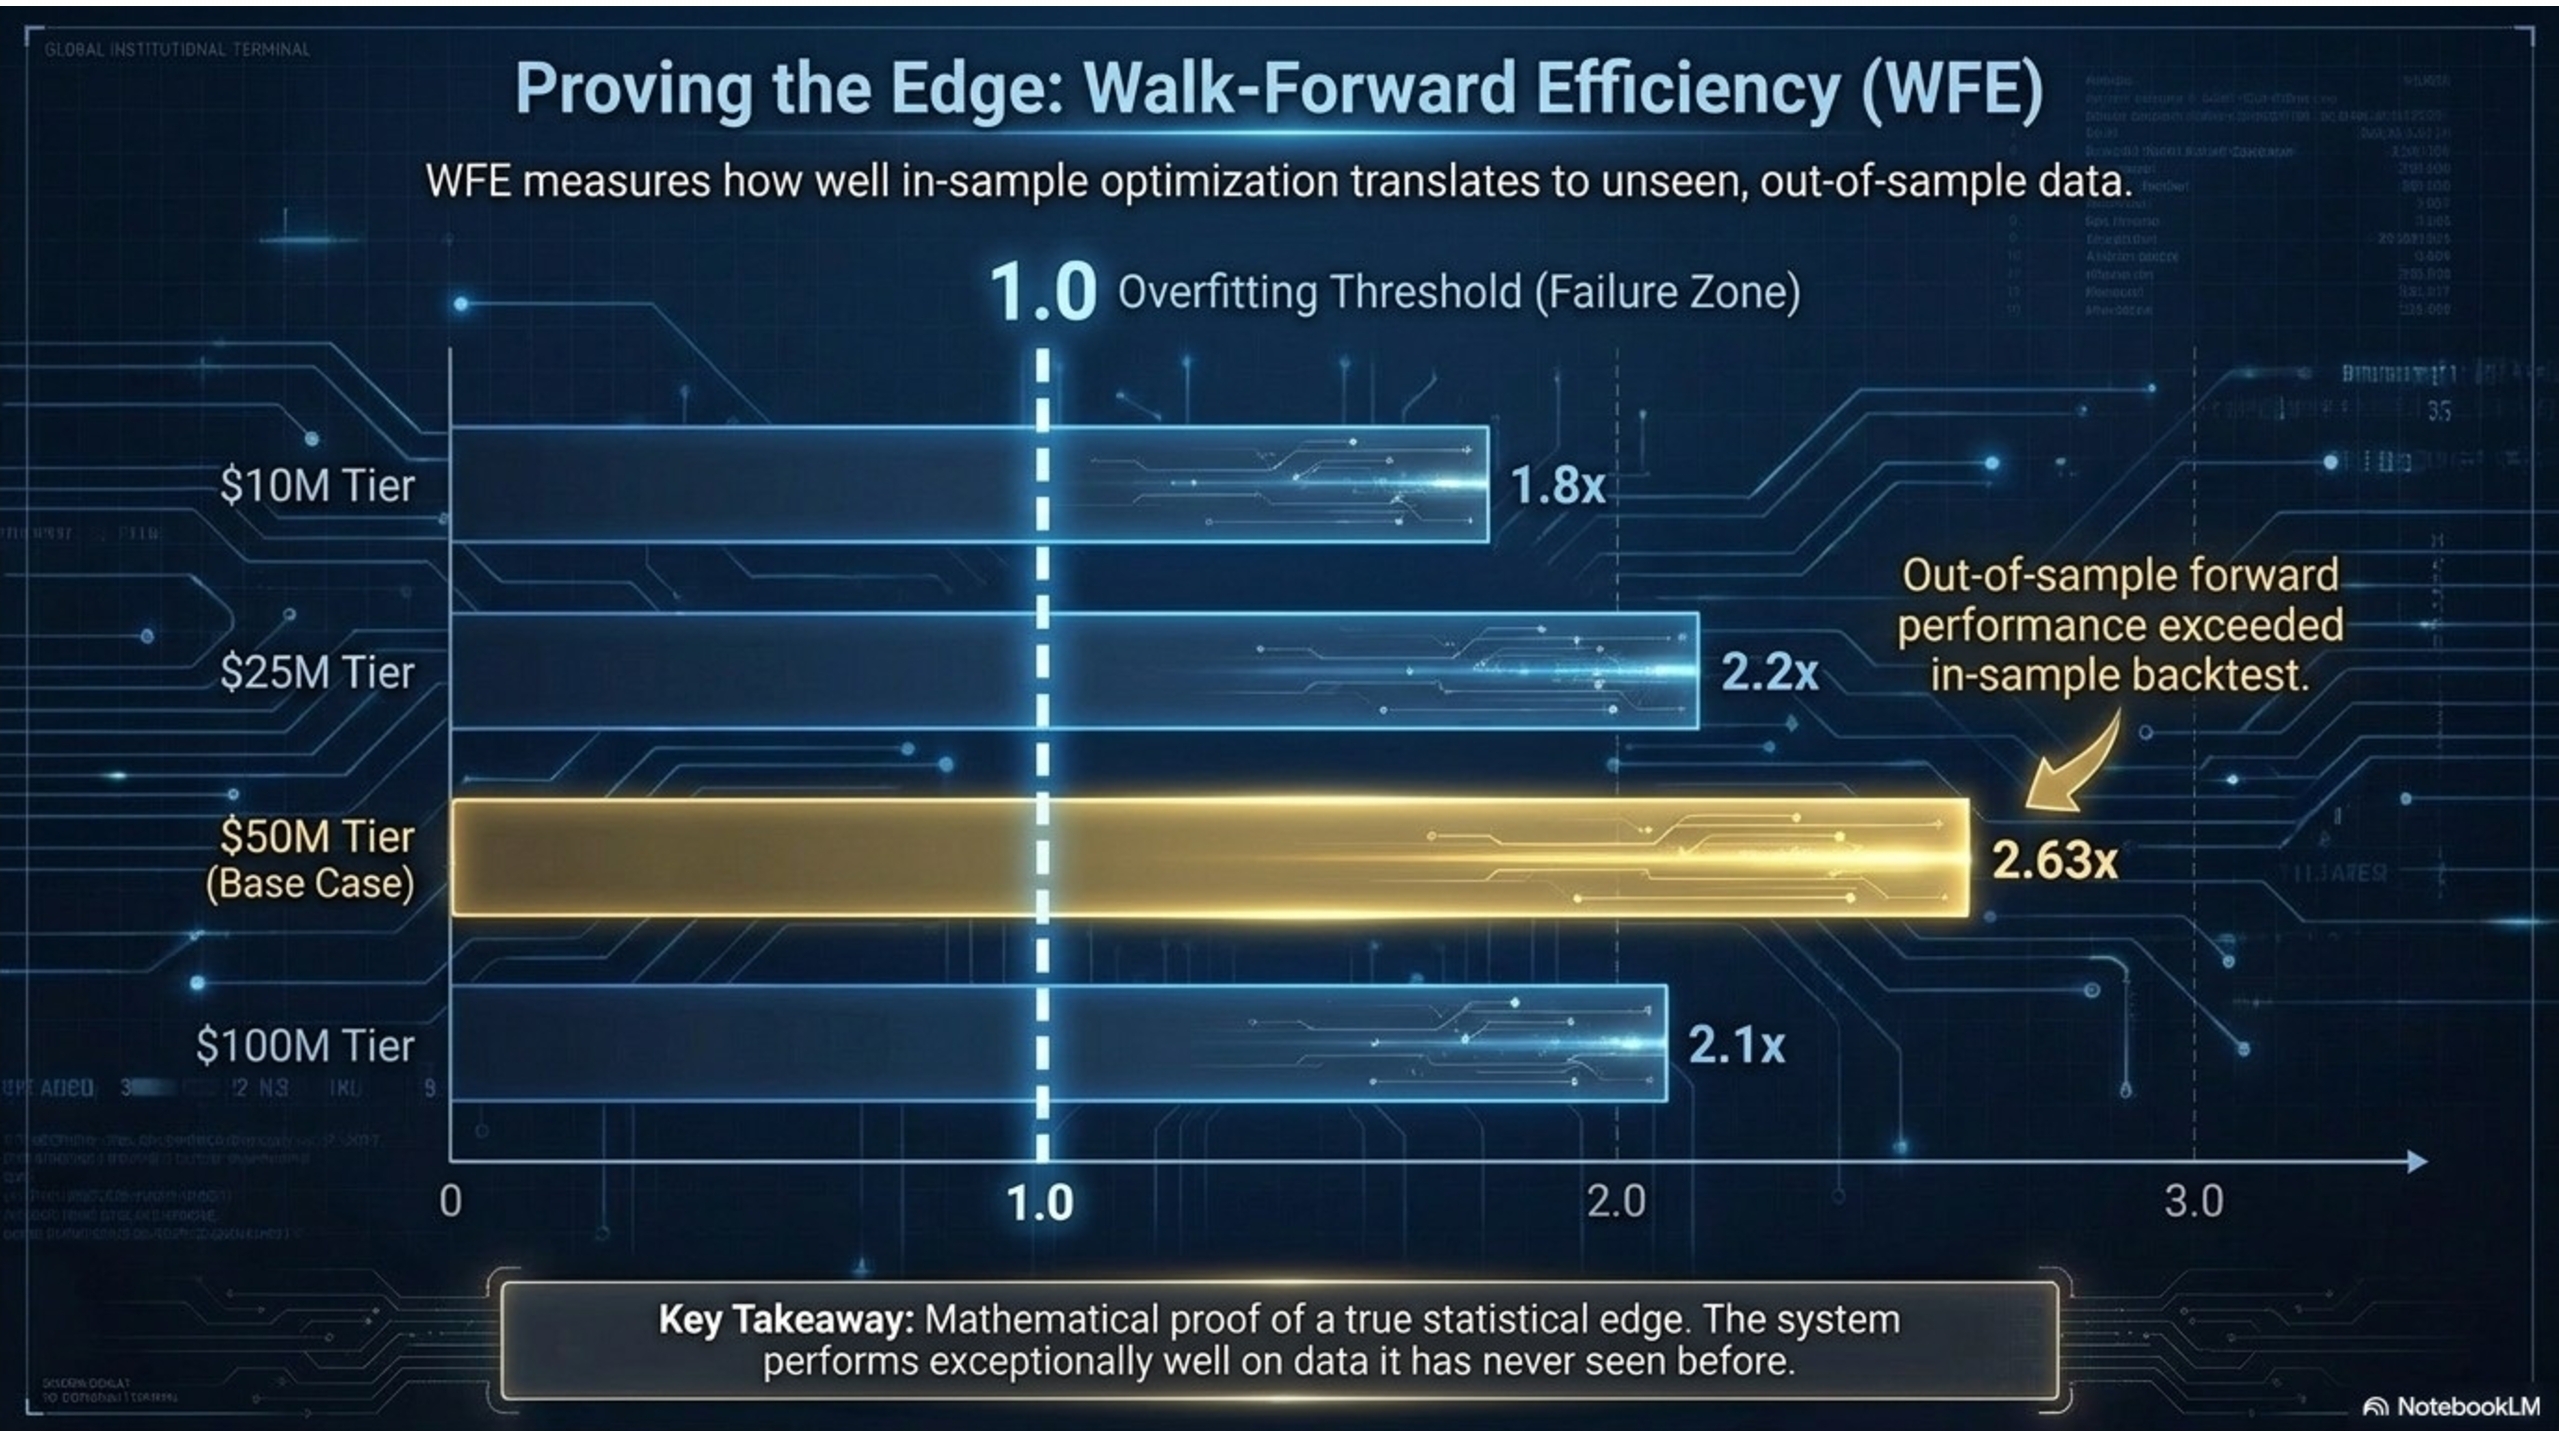
Walk-Forward Efficiency (WFE) 2.63x (Forward performance exceeded backtest)
Z-Score -74.28 (Strong negative serial correlation)
Statistical Confidence 99.74% (Confidence in mean reversion logic)
Sharpe Ratio 2.24 (Out-of-sample validated)
These metrics represent a statistically robust profile that meets the stringent requirements of institutional due diligence, confirming a systemic edge over a high-volume trade sample.
4. Leadership and Institutional Vision
The X.7 project was founded by Ayman Qzzaah, a Quantitative Strategy Developer with a decade of financial market expertise. His background in International Business Administration provides a unique synergy of administrative rigor and algorithmic precision, moving the engine from a localized research initiative to a mature institutional solution.
Strategic Trajectory: The project is positioned for the establishment of a dedicated hedge fund and the continued expansion of an advanced algorithmic ecosystem. The X.7 Swing Intraday engine is mathematically validated, operationally mature, and prepared for immediate large-scale institutional capital allocation.
A sophisticated algorithmic trading system specifically designed to accommodate large institutional capital, validated across 7.3 years of historical data with 99% modeling quality.
Most algorithmic trading systems in the markets suffer from three fatal problems: overfitting, which leads to failure in live markets; capacity erosion when capital is increased; and the operational risks associated with "black box" funds. The majority of these systems are designed for small retail accounts and fail completely when attempting to scale them to an institutional level.
The X.7 system offers a comprehensive institutional solution based on the "systematic average reversal" architecture for gold. The system features "inverse scalability," where the drawdown decreases and the Sharpe ratio improves as allocated capital increases. The system addresses the shortcomings of traditional trading through a rigorous "validation pipeline" that ensures the statistical edge remains real and not a result of chance.
Way Forward Efficiency (WFE): The system achieved a ratio of 2.63x, meaning that out-of-sample performance exceptionally exceeded in-sample performance. Value Realized: In a reference case of $50 million in capital, the system generated a final balance of $393.9 million (688% return) during the validation period (2024-2026).
Max Drawdown: Only 6.41% with a fast payback time (2-6 weeks). Statistical Proof: A Z-score of -74.28 demonstrates the system's sequential reliability and strong statistical logic with a 99.74% confidence level.
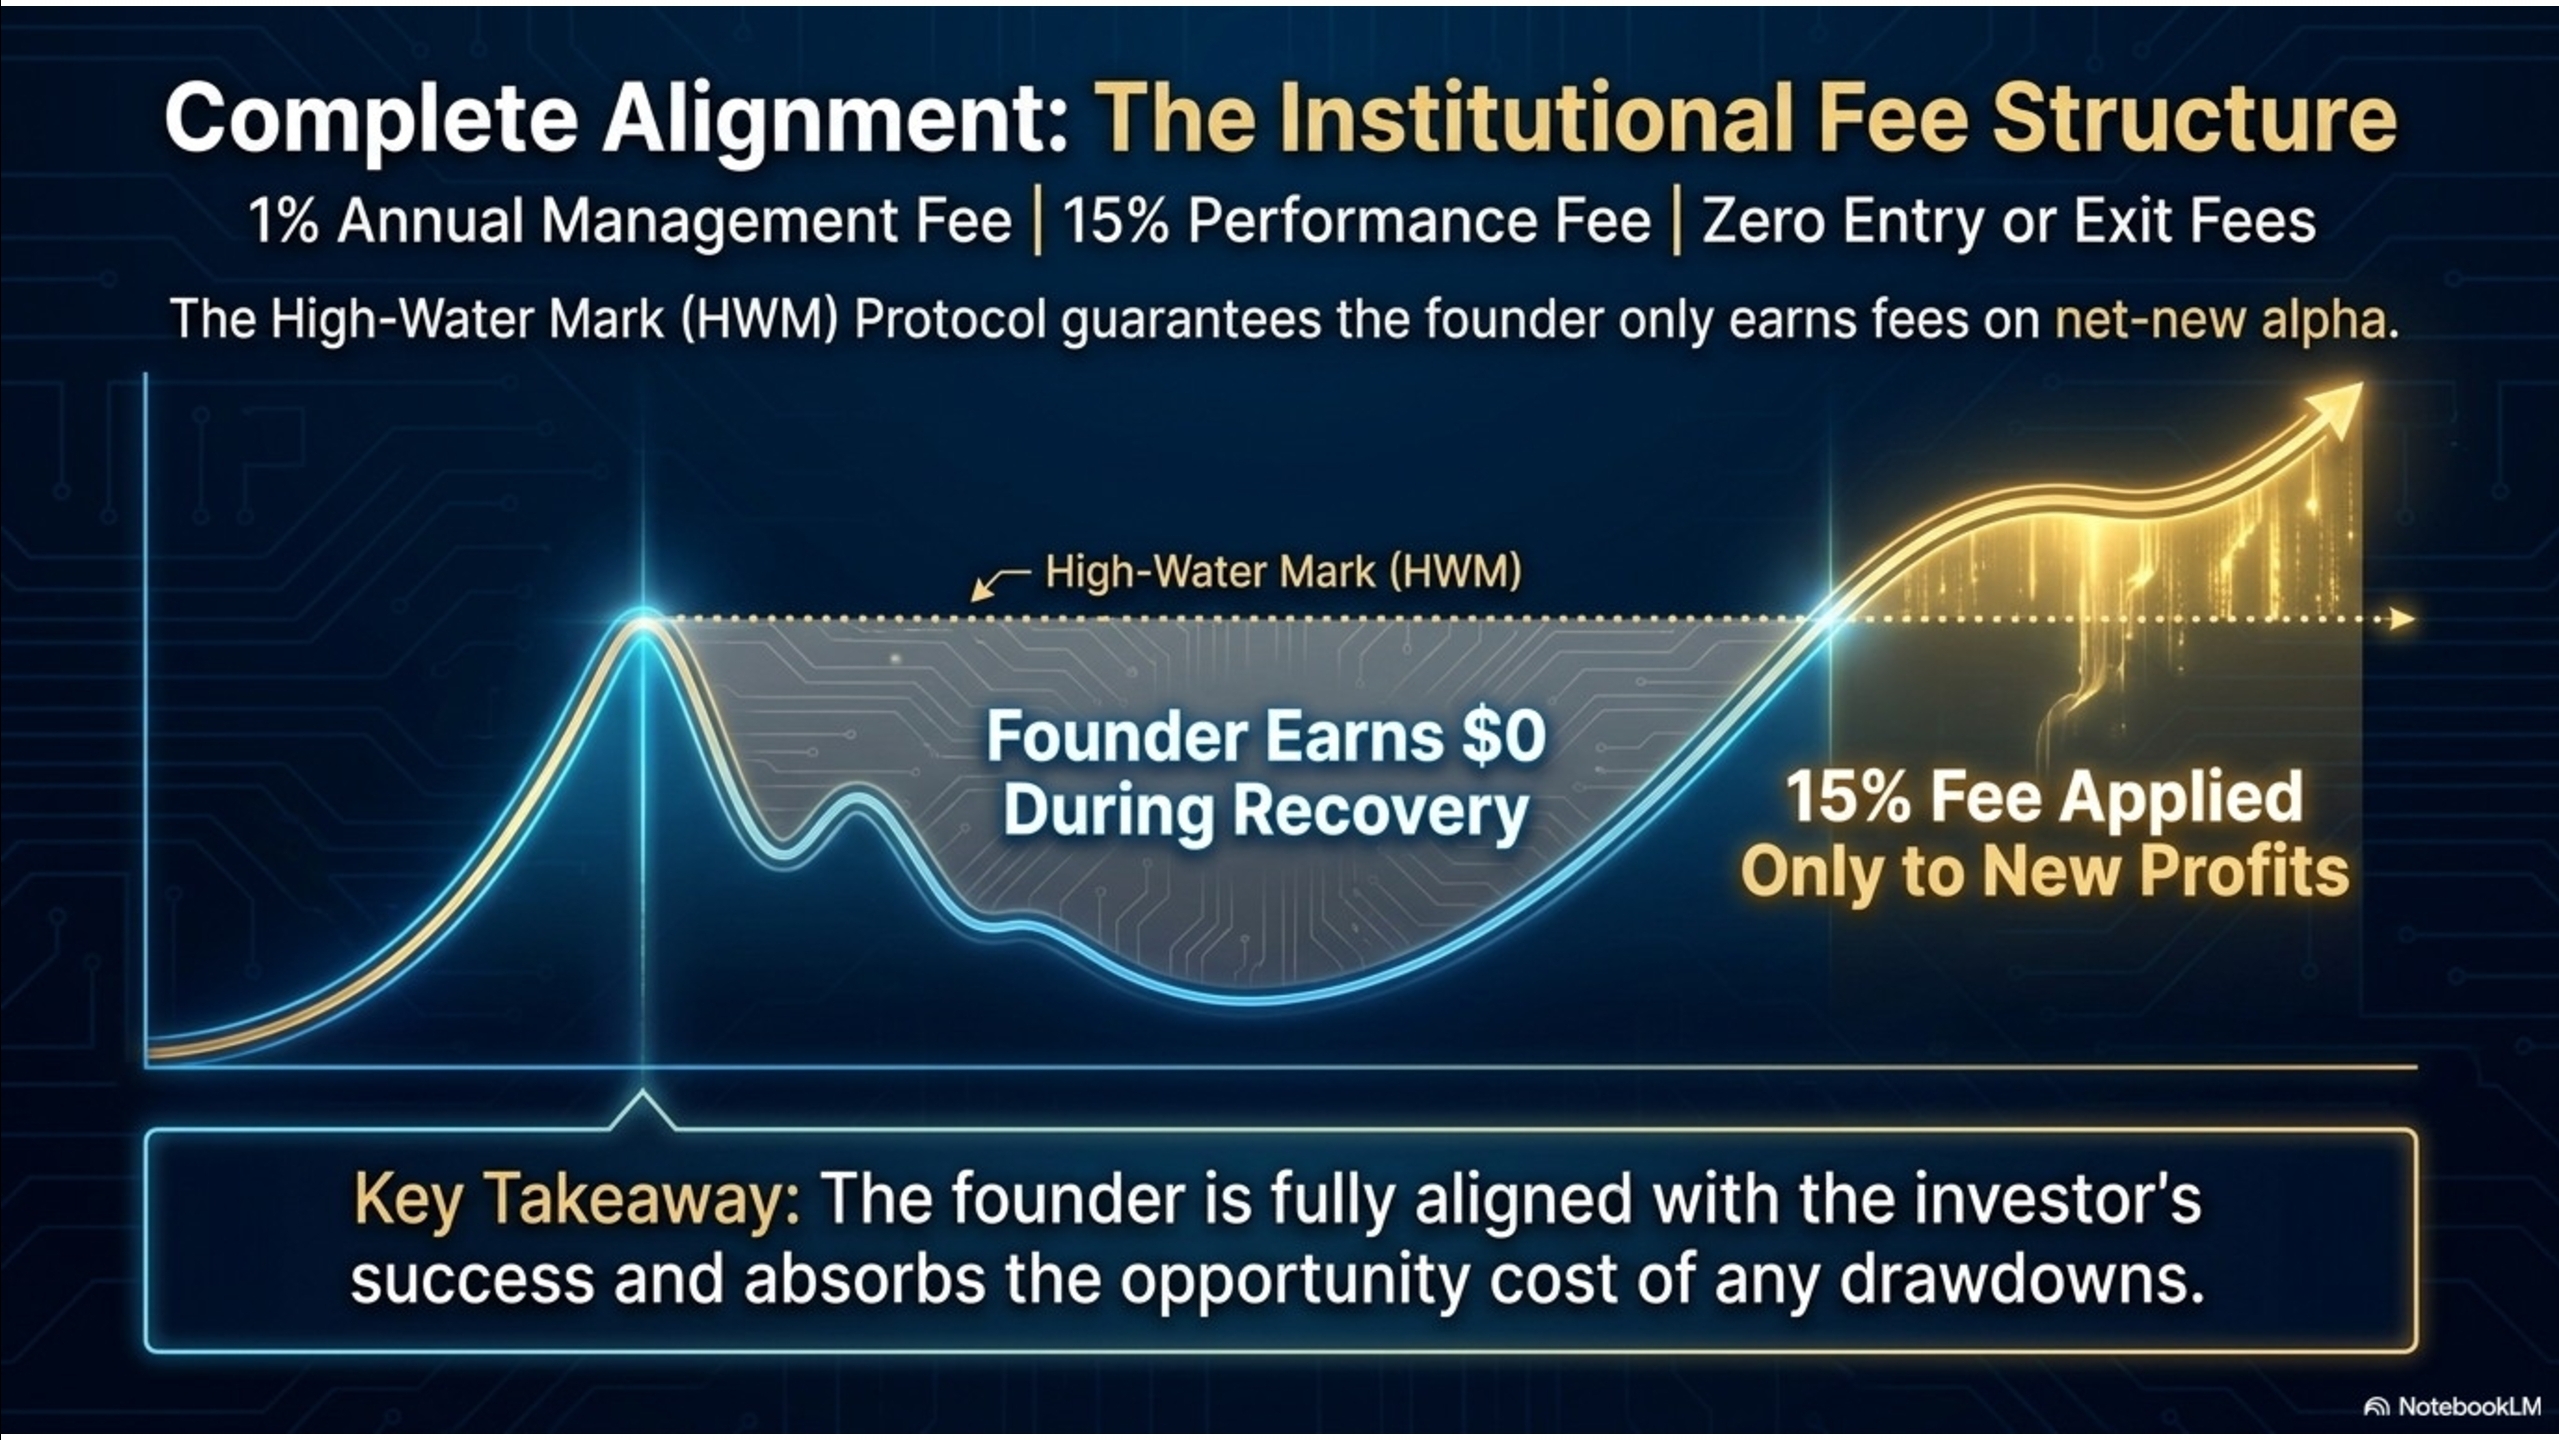
Management fees: 1% annually, payable upfront and calculated on the initial capital. This percentage is subject to change depending on the initial capital size. Performance fees: 15% based on the principle of "achieving a profit higher than the account's last recorded peak," ensuring complete alignment of interests with the investor.